Chapter 6: The Money Behind the Threats
George called an emergency meeting with Linda and the association’s attorney.
This time, Karen was not permitted to control the agenda.
The attorney, Caroline Price, had represented condominium associations and homeowners associations throughout Michigan for more than twenty years.
She understood the difference between a president exercising legitimate authority and a president acting beyond the powers granted by governing documents.
She also understood that accusations of financial misconduct required careful handling.
The $38,400 transfer had not been completed.
The bank’s authorization procedures required additional approval, and George had declined to provide it.
Caroline advised the board to preserve the relevant records, suspend disputed discretionary transfers pending review, and engage an independent accountant.
She also recommended that the board seek independent legal guidance concerning Karen’s conduct because the association’s interests might conflict with those of its president.
Karen received notice of the review.
She responded with an angry email accusing the board of disloyalty.
Then she stopped answering questions.
The independent accountant began with the previous year’s water infrastructure assessment.
The numbers were worse than Walter had expected.
The HOA had collected $57,800.
Some money had paid for legitimate maintenance.
Other funds had been transferred into accounts used for general association expenses.
Several payments had gone to Lakeshore Community Consulting.
The invoices described administrative planning, compliance coordination, and infrastructure oversight.
But the descriptions were vague.
No corresponding reports or work products could initially be located.
The accountant requested the company’s ownership information.
The registered business address matched a small commercial office leased by Karen’s adult nephew, Brian Whitmore.
Brian was thirty-four and operated a property management consulting business.
The family relationship did not automatically make the payments improper.
But it raised serious questions about conflicts of interest, disclosure, and whether the services had actually been performed.
The accountant continued reviewing invoices.
One payment was described as an emergency water system compliance review.
The cooperative had no record of requesting such a review.
Another invoice claimed payment for contractor coordination during a pipe replacement project.
The maintenance contractor confirmed that no such replacement project had occurred.
A third charge covered the preparation of enforcement notices.
Those notices included the letters Karen had sent threatening residents with utility restrictions.
Daniel learned about the findings during a meeting with Caroline and several board members.
He was surprised by how little satisfaction he felt.
He had expected that discovering financial irregularities would bring relief.
Instead, he thought about the neighbors who had paid assessments from retirement savings, fixed incomes, and carefully managed household budgets.
Margaret had postponed replacing her aging refrigerator to afford the previous year’s assessment.
Robert Gaines had canceled a planned visit to his daughter in Arizona.
Daniel himself had delayed repairs to his dock.
The money represented real sacrifices.
Karen had treated it as something she could demand without explanation.
The accountant’s preliminary report identified multiple transactions requiring further investigation.
It did not conclude that every payment was fraudulent.
Some expenses might ultimately prove legitimate.
Others lacked adequate support.
But the pattern was serious enough for Caroline to recommend that the board refer the findings to the appropriate authorities and consider legal action to recover any improperly spent funds.
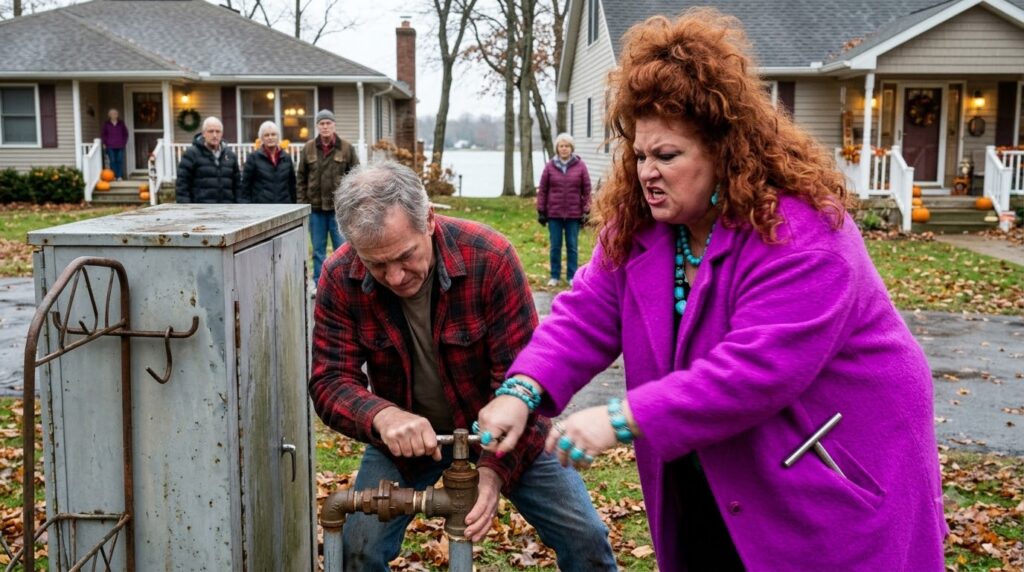
Meanwhile, the cooperative trustees formally addressed the Thanksgiving incident.
Their written report confirmed that Karen had not been authorized to operate the shared valve.
The cooperative also determined that Daniel’s actions had been taken during an unauthorized interruption of service.
Although residents were instructed not to operate utility equipment except in genuine emergencies, the trustees found no basis for Karen’s claim that Daniel had committed an HOA infrastructure violation.
They recommended that the association withdraw the fine.
The board agreed.
Daniel received a formal notice canceling the $2,500 penalty.
The letter also acknowledged that the disputed $1,200 assessment remained subject to review.
He read it at his kitchen table.
For the first time since Thanksgiving, he felt the pressure in his chest begin to ease.
But the larger problem remained.
Karen still refused to resign.
She insisted the accountant had misunderstood the records.
She claimed the consulting company had performed valuable services that the board simply failed to appreciate.
And she began contacting residents individually, warning that removing her would lead to expensive lawsuits and higher HOA dues.
Some homeowners believed her.
Others were frightened by the possibility.
Cedar Point Shores was becoming divided.
Caroline explained that removing an elected president could require specific procedures under the association’s bylaws.
The board might be able to remove Karen from an officer position, but removing her as a director would require a membership vote.
Walter reviewed the bylaws.
A special membership meeting could be called with sufficient homeowner support.
Helen began collecting the necessary signatures.
The effort moved slowly.
Some residents were traveling.
Others wanted more information.
A few feared retaliation.
Then something unexpected happened.
Patricia Lowell, the recovering treasurer, contacted George.
She had learned that her signature appeared on the Thanksgiving violation notice.
She was furious.
Patricia said she had never authorized the fine.
She had never approved shutting off the water.
And she had never signed the document.
More importantly, she had retained copies of several financial records Karen had asked her to approve earlier that year.
Patricia had refused because the supporting invoices were incomplete.
Those records included emails in which Karen instructed her to process payments despite the missing documentation.
Patricia had kept them because she was concerned about her responsibilities as treasurer.
Now she was ready to provide them to the accountant.
Her decision changed the investigation.
For the first time, the board had evidence from someone who had worked directly with Karen on the disputed transactions.
And the residents finally had enough support to call a special membership meeting.